A payment account
With its own IBAN, opened in the beneficiary’s name. It receives transfers and can send them, if you allow it.
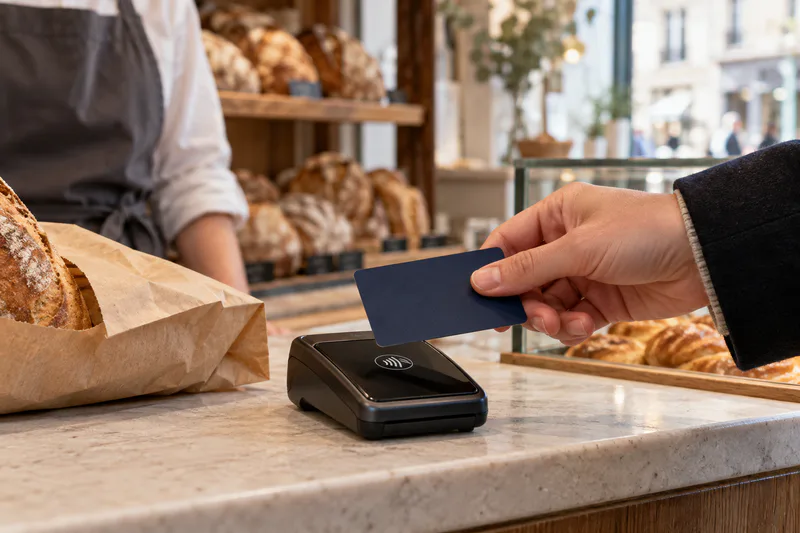
Every beneficiary of your programme receives their own payment account. They pay in store, online and abroad, within the frame you have set, without ever advancing the money.
Not a prepaid card. The card is backed by a payment account with an IBAN. It does not need topping up: it draws on the envelope you opened, and refuses whatever falls outside your rules.
What is opened
Everything is open the moment the programme starts. There is nothing to install on your side.
With its own IBAN, opened in the beneficiary’s name. It receives transfers and can send them, if you allow it.
Accepted wherever cards are: in store, online, abroad. It is not a prepaid card to top up.
To pay a supplier who has no terminal, or to settle an invoice.
The remaining balance, past payments, the rules that apply. The beneficiary knows before paying.
Your rules
They are checked at every operation, before it is executed. You can change them while the programme runs, without reissuing cards.
The beneficiaries enrolled in the programme, and nobody else.
Example: 12 designated technicians
A ceiling per operation, per day, per month, or for the whole duration.
Example: €600.00 per person
An opening period, with a start date and an end date.
Example: from 1 March to 31 December
A list of suppliers, or authorised categories of shops.
Example: referenced suppliers
A geographic area: a town, a department, a country, the whole world.
Example: metropolitan France
Online payment allowed or not, cash withdrawals allowed or not.
Example: online yes, withdrawals no
Deliverables and how it works
The proof covers the payment: amount, supplier, date, rule applied. The rest is written here, so that nobody discovers it afterwards.
The rule bears on the supplier, the category, the amount and the date. It does not read the list of items.
The proof covers the payment, not what was delivered afterwards.
Electronic money bears no interest and is not covered by the deposit guarantee scheme.
What we show before any commitment. Before any commitment, we run an authorised payment, a justified refusal and a refund, then reconcile the balance and the statuses through to settlement of the supplier.
A worked example
A network allocates an equipment budget to its partners. Each of them pays the authorised suppliers with the payment method validated for the programme, and the finance department follows the state of every operation.
Situation and values given as an example. No result and no price is announced.
Frequently asked questions
Yes. An account with an IBAN, incoming and outgoing transfers. A universal payment card, not a prepaid card. Online payment, the QR code and the app, usable anywhere in the world. Your programme’s rules decide where and what they work for.
100% of operations are checked before execution. A payment outside the rules is refused, and the reason is recorded. The beneficiary knows why straight away. Refunds and remaining balances follow the programme contract. An end date does not make the funds disappear.
Who, when, how much, where and what for. You choose the registered beneficiaries, the ceilings per transaction, per day or per month, the period, the authorised suppliers or categories, the geographic area. You allow online payment and cash withdrawals, or you do not. For example: €600.00 per household, at food suppliers in the chosen area, for three months.
Tell us who funds the programme, who uses the funds and what it must allow people to pay for. We identify the rules, what you must be able to track and the points that need validation.